NRG Nguyen Realty Group
The Buyer's
The Buyer's
Guide
Every inspired move starts with a clear plan.
Andrew and Jassey Nguyen · Metro Atlanta
Every inspired move starts with a clear plan.
Andrew and Jassey Nguyen · Metro AtlantaThis guide is for anyone preparing to buy a home in metro Atlanta: a first purchase, a move across town, a relocation for work, or a change of pace after years in one place.
It follows the purchase in the order it happens in Georgia, from your numbers and your pre-approval to the offer, due diligence and closing day.
Along the way are the costs to expect, the checklists that keep each stage on track and the words worth knowing. When a question comes up, bring it to our team.
Andrew and Jassey Nguyen
Read it start to finish once. Then come back to the page you need, when you need it.
 01 · A note from us
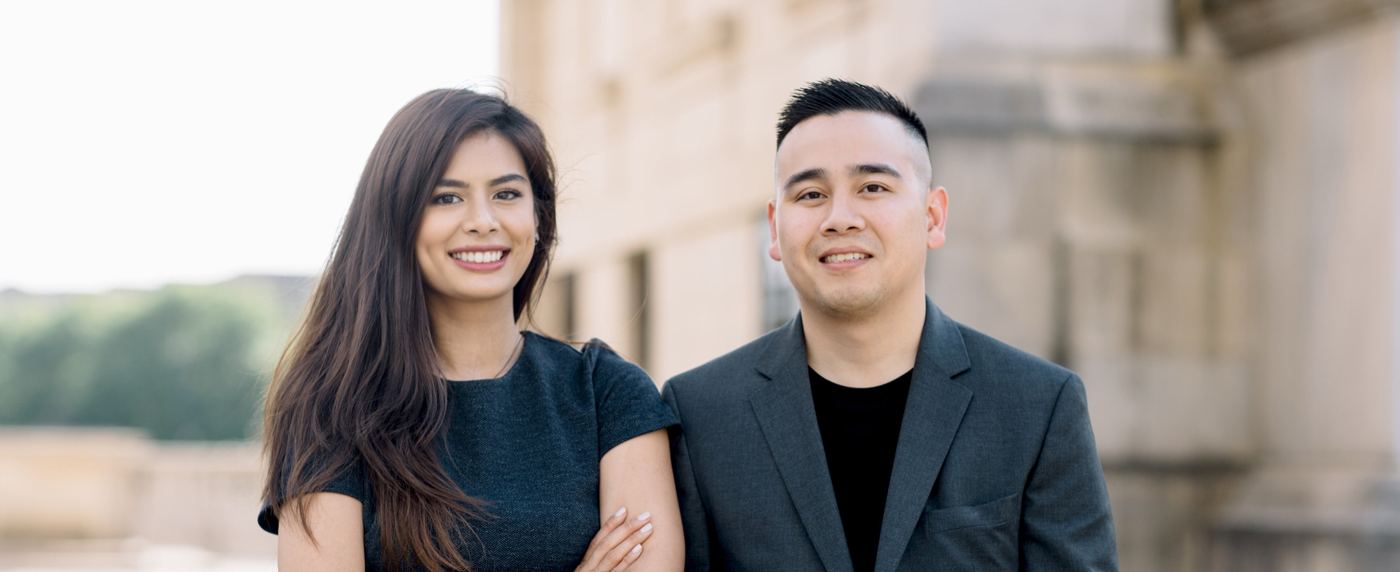
We know buying a home is one of the biggest decisions you will make. Our team is here to give you thoughtful, personal guidance from the first conversation to the day you get the keys, and we take real pride in the relationships we build along the way.
We lead with research and education. Real estate has grown complex, and you deserve a trusted resource who brings you clear information and honest advice.
Whether you are buying your first home or your fifth, we shape our approach around what you need. Expect clear communication, steady guidance and a team that stays with you through every step.
Beyond real estate, we love exploring new restaurants in and around Atlanta, traveling with our daughters and spending time with our pups.
We are honored to be part of this chapter with you, and we look forward to helping you find the home that fits.
We're glad you're here.
Andrew and Jassey Nguyen
Clarity before commitment.
Eight steps, in the order they happen in Georgia.
Decide the monthly payment that lets you live well, then work back to a price with our mortgage calculator. That number is yours to set, before anyone shows you a home.
A lender reviews your income, credit and savings and puts a figure in writing. Sellers expect to see it with your offer.
We sit down together: your goals, the process, the costs to expect and how we work. You sign a buyer brokerage agreement before we tour, and it spells out what we do for you and how we are compensated. You also take home your buyer homework: the purchase and sale agreement, to read before any offer.
New listings come to you as they hit the market. We tour the ones worth your time and tell you simply what we see.
Price, earnest money, the length of your due diligence period, closing date and any seller contribution. We advise you on every term, so the offer competes and your protection periods stay in place. Every decision is yours.
Once the offer is accepted, the clock starts. Inspections, insurance quotes and a careful look at the home happen inside this window.
The lender orders the appraisal and finishes underwriting. We keep the lender, the closing attorney and the other agent on the same timeline.
In Georgia, a closing attorney handles the closing. You review the numbers, sign, the deed is recorded and the keys are yours.
Tap a line to check it off. It stays checked on this phone.
Tap a line to check it off. It stays checked on this phone.
Know where every dollar goes before you make an offer. For a quick estimate of your monthly payment and cash to close, try our mortgage calculator. Your lender's Loan Estimate gives the exact figures for your loan.
| Cost | What to know |
|---|---|
| Earnest money | A deposit that shows the seller you are serious. It is held until closing and credited toward what you owe. |
| Inspections | Paid during due diligence, usually directly to the inspector. |
| Appraisal | Ordered by your lender, usually paid when it is ordered. |
| Down payment | Your share of the price, due at closing. |
| Lender, title and closing attorney fees | Loan fees, the title search and title insurance, and the closing attorney's fee for preparing the closing. |
| Georgia transfer tax | $1 for every $1,000 of the price, so $500 on a $500,000 home. The standard Georgia contract has the buyer pay it. |
| Georgia intangible tax | $1.50 for every $500 of a new loan, so $1,200 on a $400,000 loan. A cash purchase has none. |
| Prepaids | The first year of homeowner's insurance and a few months of taxes and insurance set aside for your escrow account. |
Who pays what follows the 2026 Georgia REALTORS® Purchase and Sale Agreement, section 3. A special stipulation in your contract can change it, and your contract always governs.
Wire fraud targets home buyers. Before you send money, call the closing attorney at their official number, one you look up yourself, and confirm the instructions out loud.
Changed instructions in an email are a warning sign, even when the email looks like it came from someone you know.
Income, work history, credit, debts and savings.
Compare a few. We are glad to share lenders our clients have trusted.
The lender reviews your file and your credit. Some charge an application fee, so ask first.
A pre-approval letter shows the amount, the loan type and the terms.
Hold steady on new credit and big purchases until you close. Changes can affect your approval.
Every lender is different. Yours will give you the exact list.
Begin with what matters most. Leave room for the home to surprise you.
 07 · The search
Search live listings on our site by area, price, beds and baths, and save the homes you like. Set an alert and new listings come straight to you.
When a home earns a closer look, we book the showing and walk it with you. Bring every question you have.
A relaxed way to get a feel for an area. Let the host know you are working with us.
After a few homes, patterns show up. We help you weigh location, condition and price side by side, so the right home stands out.
Make inspired moves.
An offer is more than a price. Earnest money, the due diligence period, the closing date and any seller contribution all shape how strong it reads. We look at what the seller needs and advise you on terms that compete while keeping you protected. The final call is always yours. And because you read the purchase and sale agreement as your buyer homework, nothing in it is new when it is time to sign.
The seller can accept, counter or decline. If they counter, you can accept, counter again or walk away. Once both sides sign, you have a binding agreement and the dates start to run.
A set number of days, written into your offer, to inspect the home, review insurance and HOA documents and decide. Under the standard Georgia contract you can end the agreement during that window, by written notice before it closes. Your contract's exact terms govern.
A licensed inspector checks the structure, roof, systems and more, then sends a report. We use it to ask for repairs or a price change, or to decide the home is not the one.
Your lender's appraiser compares the home to recent sales nearby. If it comes in below your price, we look at the options together: renegotiate, bring more cash, or a mix.
We track every deadline in the contract and keep the lender, the closing attorney and the other agent moving on the same dates.
 01
A last look before closing to confirm the home is as agreed and any repairs are done.
 02
When you finance, your lender sends it at least three business days before closing. It shows your final loan terms and the cash you need to close.
 03
Send your funds at least one business day before closing, the way the closing attorney asks and after you confirm the instructions by phone, so nothing holds up your closing.
 04
At the closing attorney's office you sign the loan documents and the closing papers. Bring a photo ID.
 05
The deed is recorded in your name and the keys are yours. Welcome home.
The keys are yours.
Need a mover, a cleaner or a handyman? Ask us for names our clients have trusted.
We absolutely love working with Andrew and Jassey!
“The first time we worked with them, we were moving from out of state, and they still managed to be with us every step of the way.”
“From start to finish, their team guided us with expertise and care, ensuring we were well-informed and confident throughout the entire process.”
“He got us a great deal when buying and also made sure we got the most of our money when selling.”
“Jassey and Andrew definitely fit the bill and we were under contract for a home 12 days.”
Each is easy to make, and each is covered in the pages before this one.
Start from the monthly payment that lets you live well, then work back to a price. That number is yours to set, before anyone shows you a home.
A pre-approval letter shows the amount, the loan type and the terms. Sellers expect to see it with your offer.
Hold steady on new credit and big purchases until you close. Changes can affect your approval.
Due diligence is a set number of days, written into your offer. Book every inspection that matters to you right away, such as a sewer scope, septic, mold or radon check, so you decide with the reports in hand.
Instructions that arrive by email are never enough on their own. Every wire is confirmed by phone first, before a dollar moves.
A licensed appraiser's opinion of the home's value, ordered by your lender.
The difference when the appraisal comes in below the price you agreed to pay.
The day the contract is fully signed and delivered. Most deadlines count from it.
Your written agreement with us: what we do for you and how we are compensated.
The Georgia attorney who conducts the closing, handles the funds and records the deed.
Fees and taxes paid at closing, beyond the down payment.
The lender's final statement of your loan terms and cash to close, sent at least three business days before closing.
A study of recent nearby sales used to judge a fair price.
A reply to an offer that changes its terms.
How long a home has been listed for sale.
Your share of the price, paid at closing. The loan covers the rest.
The window written into your contract to inspect, review and decide.
Your good-faith deposit, held until closing and credited to you there.
The part of the home's value you own outright: value minus what you owe.
An offer term that raises your price by set steps, up to a limit, if another offer comes in higher.
An account your lender keeps to pay your property taxes and insurance each year.
A Georgia tax on a new loan: $1.50 for every $500 borrowed.
A lender's written review of your finances and how much they are prepared to lend.
The amount you borrow, separate from interest and fees.
The lender's promise to hold your interest rate for a set time.
Money from the seller toward your closing costs, agreed in the contract.
Protection against problems with the home's ownership history.
A Georgia tax on the sale: $1 for every $1,000 of the price.
The lender's final review of you, the loan and the home before approval.
Your notes stay on this device.